In your own warehouse, a stock variance is a cost problem. In a third-party logistics (3PL) warehouse, it is a trust problem. Two cartons short on one client's stock is that client's report, that client's angry phone call, and potentially that client's renewal decision. This is why keeping client stock honest is the central discipline of multi-client inventory management, and why the debate over cycle count vs physical inventory has a clear winner for day-to-day control. For a complete overview of the topic, see the complete guide to 3PL inventory management.
The short answer
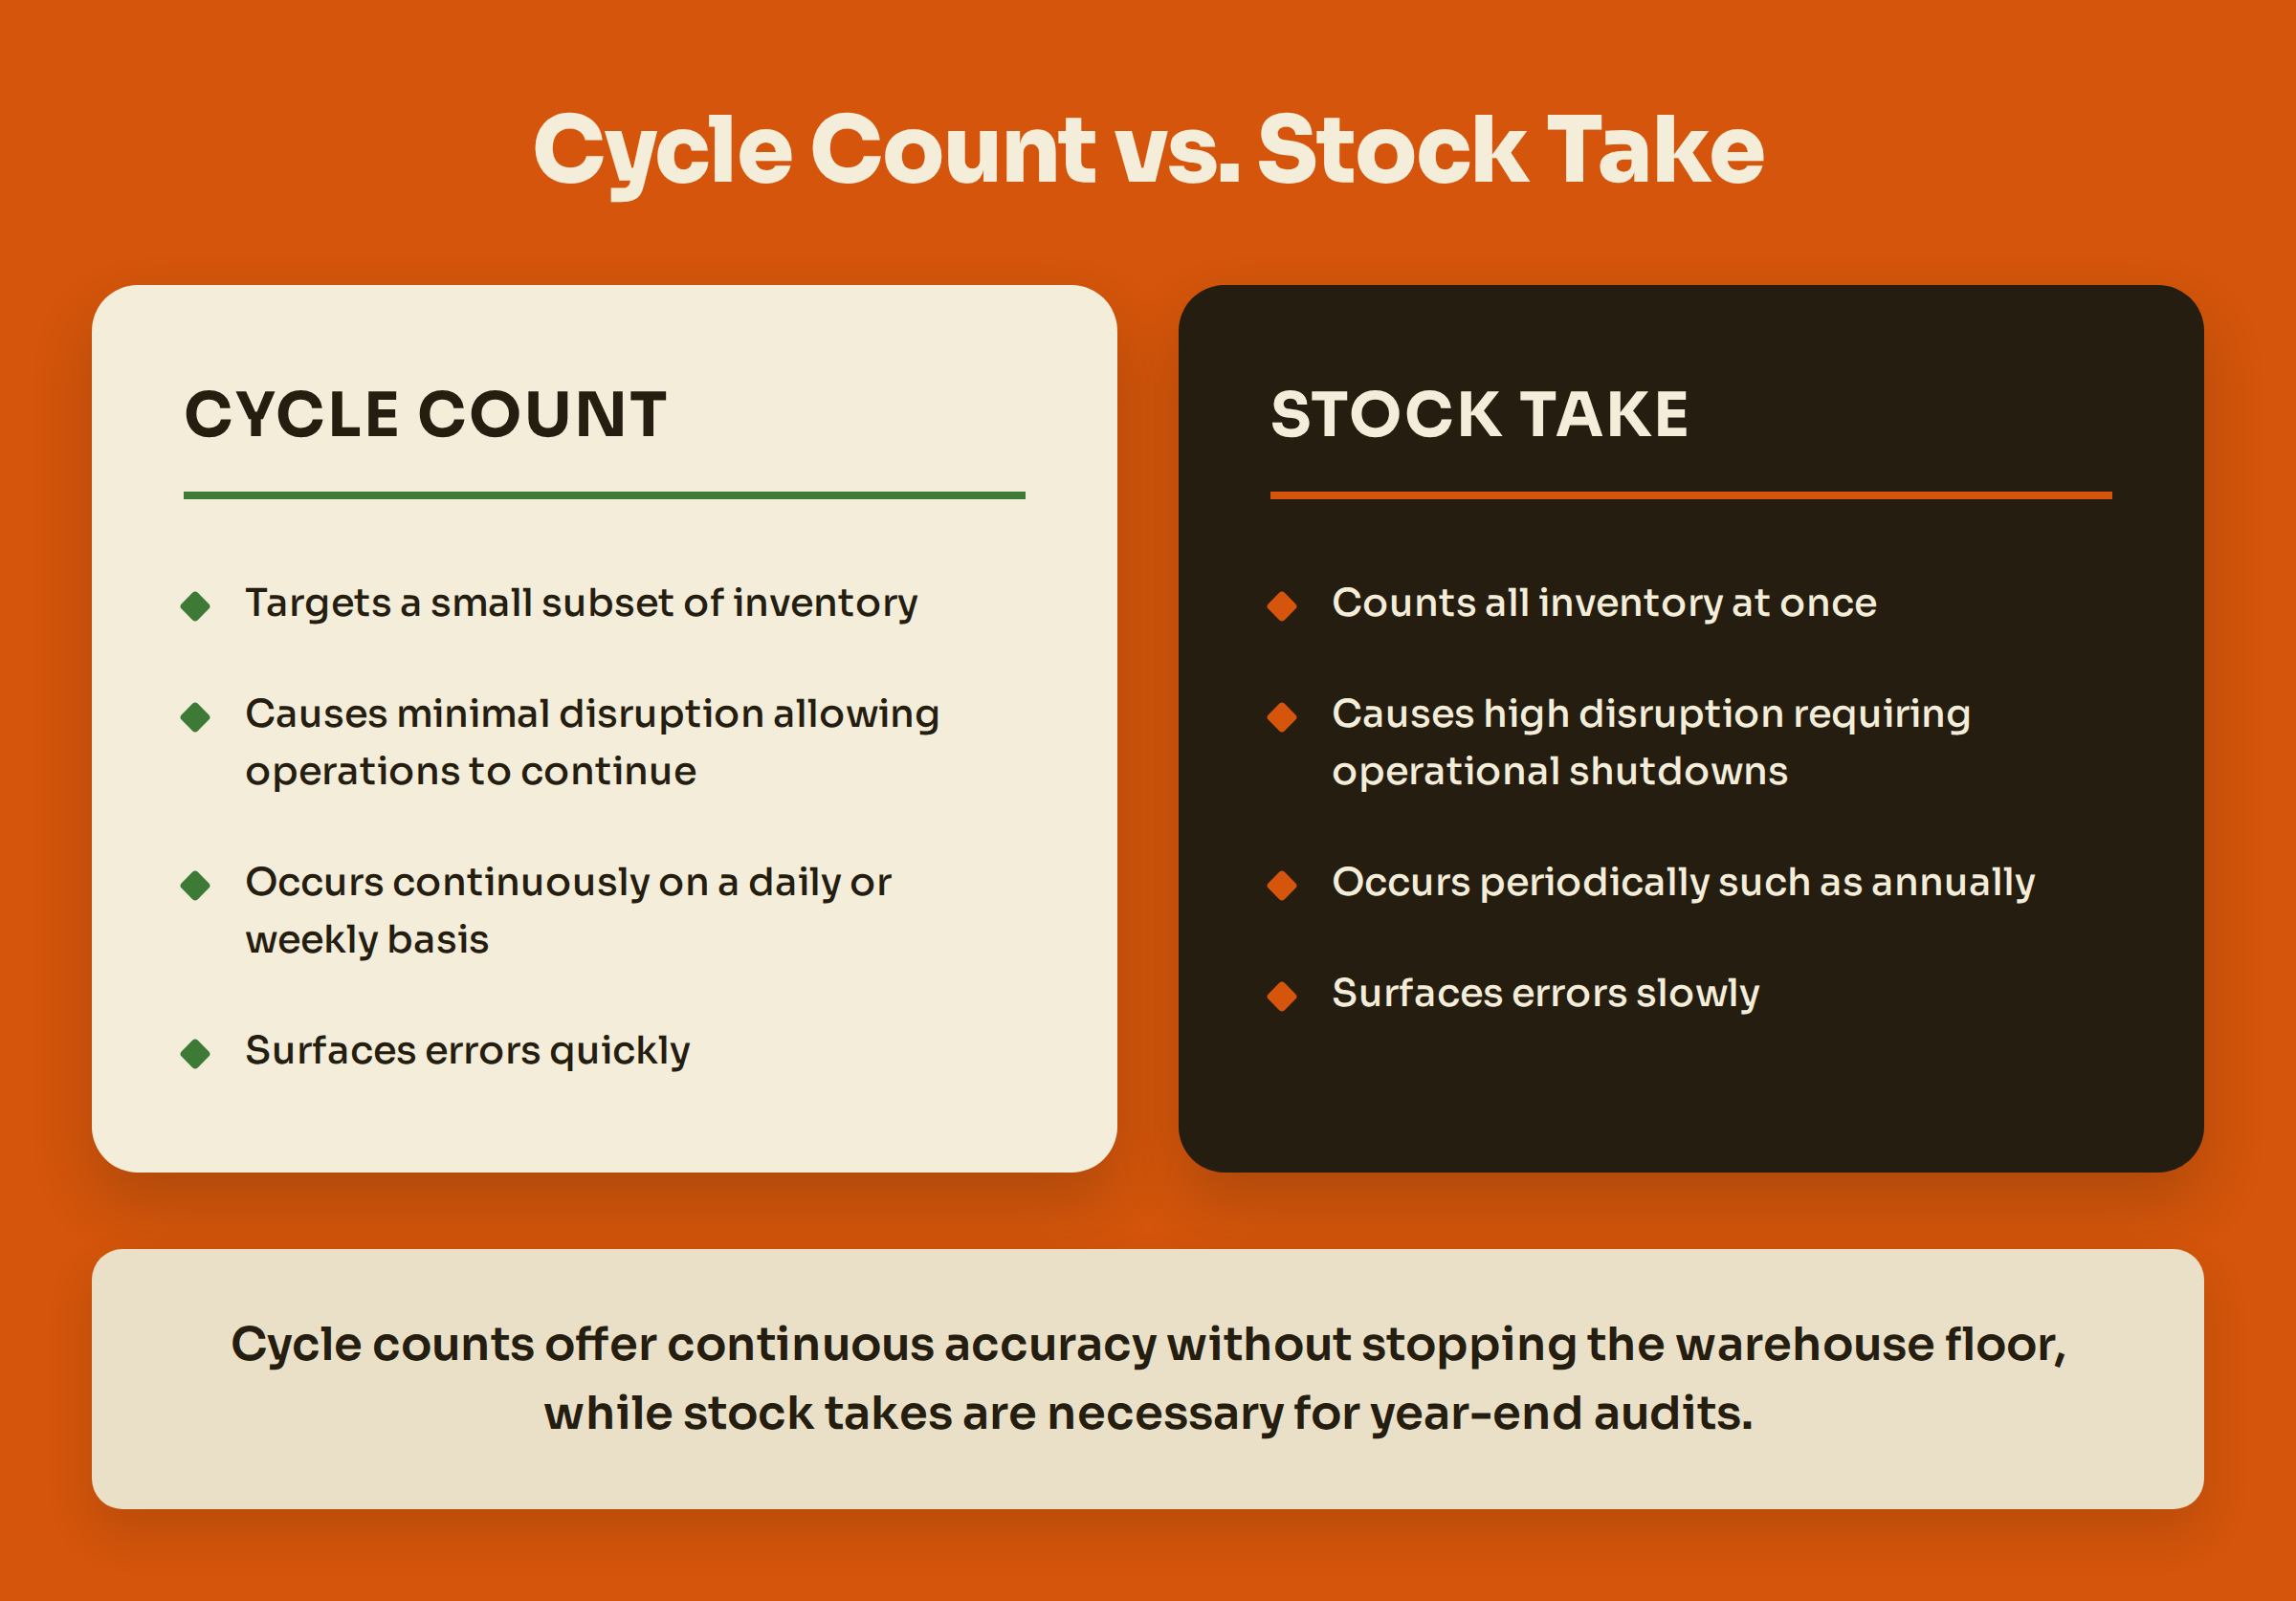
A cycle count is a rolling check of a small, specific part of your inventory—a single bin, a zone, or one client’s SKUs—while operations continue. A stock take, or physical inventory, is a wall-to-wall count of everything at once, usually requiring you to pause operations. For a 3PL, rolling cycle counts are the everyday discipline that maintains inventory accuracy and client trust. The full stock take is the scheduled, large-scale exception.
The core difference in the cycle count vs stock take debate for a 3PL is speed and focus. Cycle counting finds errors while the trail is still warm—a mis-pick from yesterday, a receiving error from this morning—and isolates the problem to a specific client. A full stock take finds every error at once, but often months after they occurred, making the investigation slow and the explanation to the client difficult.
Cycle count vs stock take, side by side
Understanding the practical difference between a cycle count and a full physical inventory (often called a stock take in the UK and India) helps you choose the right tool for the job. The stocktake meaning is simple: a complete count of all stock at a point in time. A cycle count is a more targeted, continuous process.
Here is how the two methods compare on the warehouse floor.
Comparison Table: Cycle Count vs. Stock Take
| Cycle Count | Stock Take (Physical Inventory) | |
|---|---|---|
| Scope | Counts a small, defined subset of inventory (e.g., by location, SKU, or client) on a recurring schedule. | Counts all inventory in the warehouse or for a specific client at a single point in time. |
| Effect on the floor | Minimal disruption. Operations continue while a specific area is briefly controlled for counting. | Highly disruptive. Often requires a full or partial shutdown of operations to freeze stock movement. |
| How often | Continuous. Can be daily or weekly for high-risk items and less frequent for slow-movers. | Periodic. Typically annual, semi-annual, or as required by a client contract or for an audit. |
| How quickly errors surface | Quickly. Discrepancies are found close to the event, making root cause analysis easier. | Slowly. Errors may have accumulated for months, making it hard to trace the cause. |
| Fit for a 3PL | Excellent. Allows for client-specific counts, targets high-risk areas, and maintains continuous inventory accuracy without stopping the floor. | Necessary for specific events like year-end audits, client onboarding, or system migrations, but too disruptive for daily control. |
Why counting is different when the stock is not yours
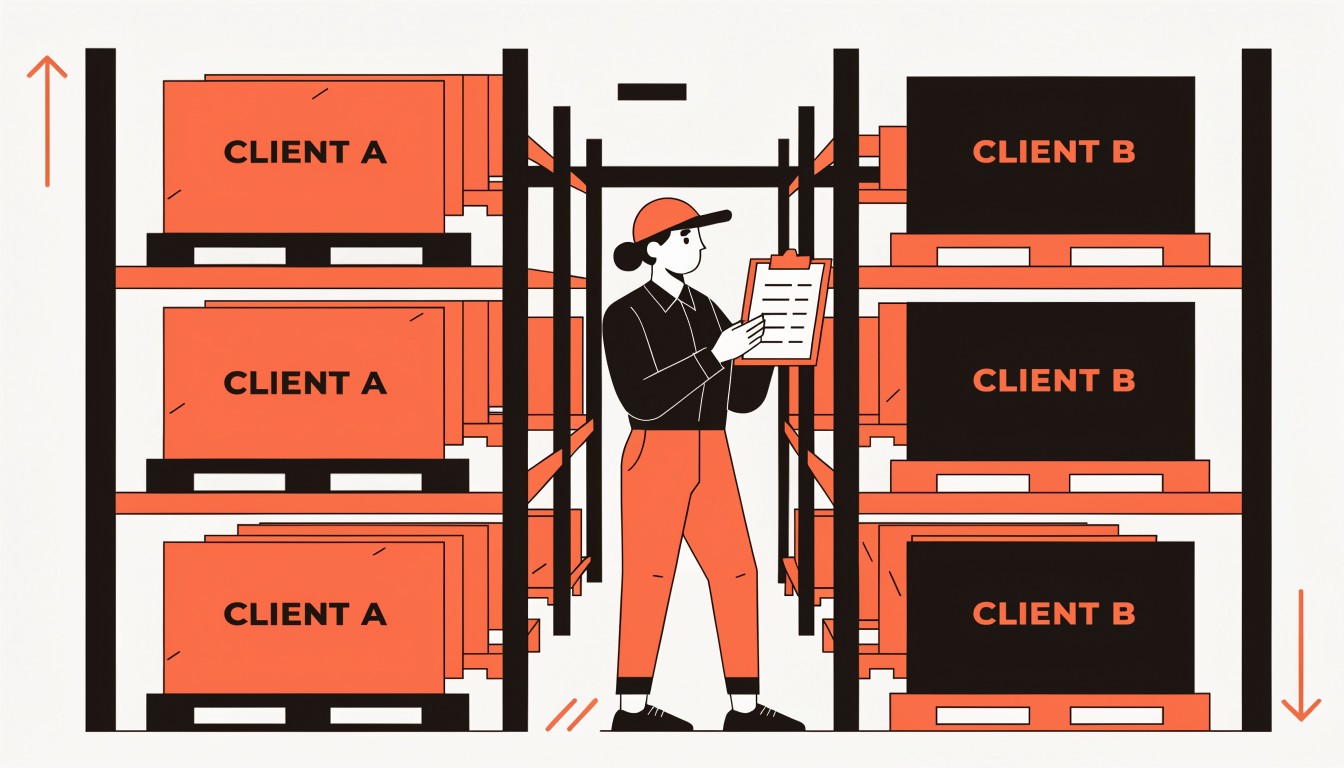
In a multi-client warehouse, you don't own the inventory; your clients do. This simple fact changes everything about inventory control. A facility-wide accuracy figure means nothing to the one client whose stock is wrong. Every count, variance, and adjustment must be resolved at the client level.
Client-Specific Inventory, Client-Specific Problems
A variance is not a "warehouse problem"—it's a specific client's problem. If you are ten units short for Client A and ten units over for Client B, your warehouse total is correct, but both clients have a serious issue. You cannot use Client B's overage to fulfill Client A's order. This is why a 3PL's WMS and operational processes must enforce strict client-specific inventory segregation. This principle is also written into law in some markets. For example, India's GST rules require warehouse operators to maintain records so that goods can be identified "item-wise and owner-wise," according to the Central Board of Indirect Taxes and Customs.
A Variance is a Trust Issue
For your own stock, a variance is a financial write-off. For a client's stock, it's a breach of trust that can damage the relationship and lead to contract termination. The conversation is not about your overall accuracy percentage; it's about why their specific order couldn't be fulfilled or why their stock balance is incorrect. This is also a direct cause of revenue leakage, as unresolved discrepancies can lead to unbilled storage for overages or costly claims for shortages.
The Audit Trail Must Be Per Client
Because each variance belongs to a client, the entire investigation and resolution process must be documented at the client level. Who counted it? When? What was the system quantity? What was the physical quantity? What was the root cause? Who approved the adjustment? This audit trail is your proof of professional diligence and is essential for resolving disputes and satisfying auditors.
How to run rolling cycle counts
Effective cycle counting is a disciplined process, not a random spot check. For a multi-client warehouse, it’s about creating a sustainable rhythm of verification that keeps every client’s stock honest without bringing your operation to a halt.
1. Cut Count Tasks by Bin, Zone, or Client
Structure your counts logically. You can generate count tasks by:
- Bin: A specific list of locations to be counted.
- Zone: All locations within a defined area, like the returns zone or a bulk storage area.
- Client: All locations containing a specific client's stock. This is ideal for preparing client-specific reports.
2. Count Fast-Movers More Often (ABC Approach)
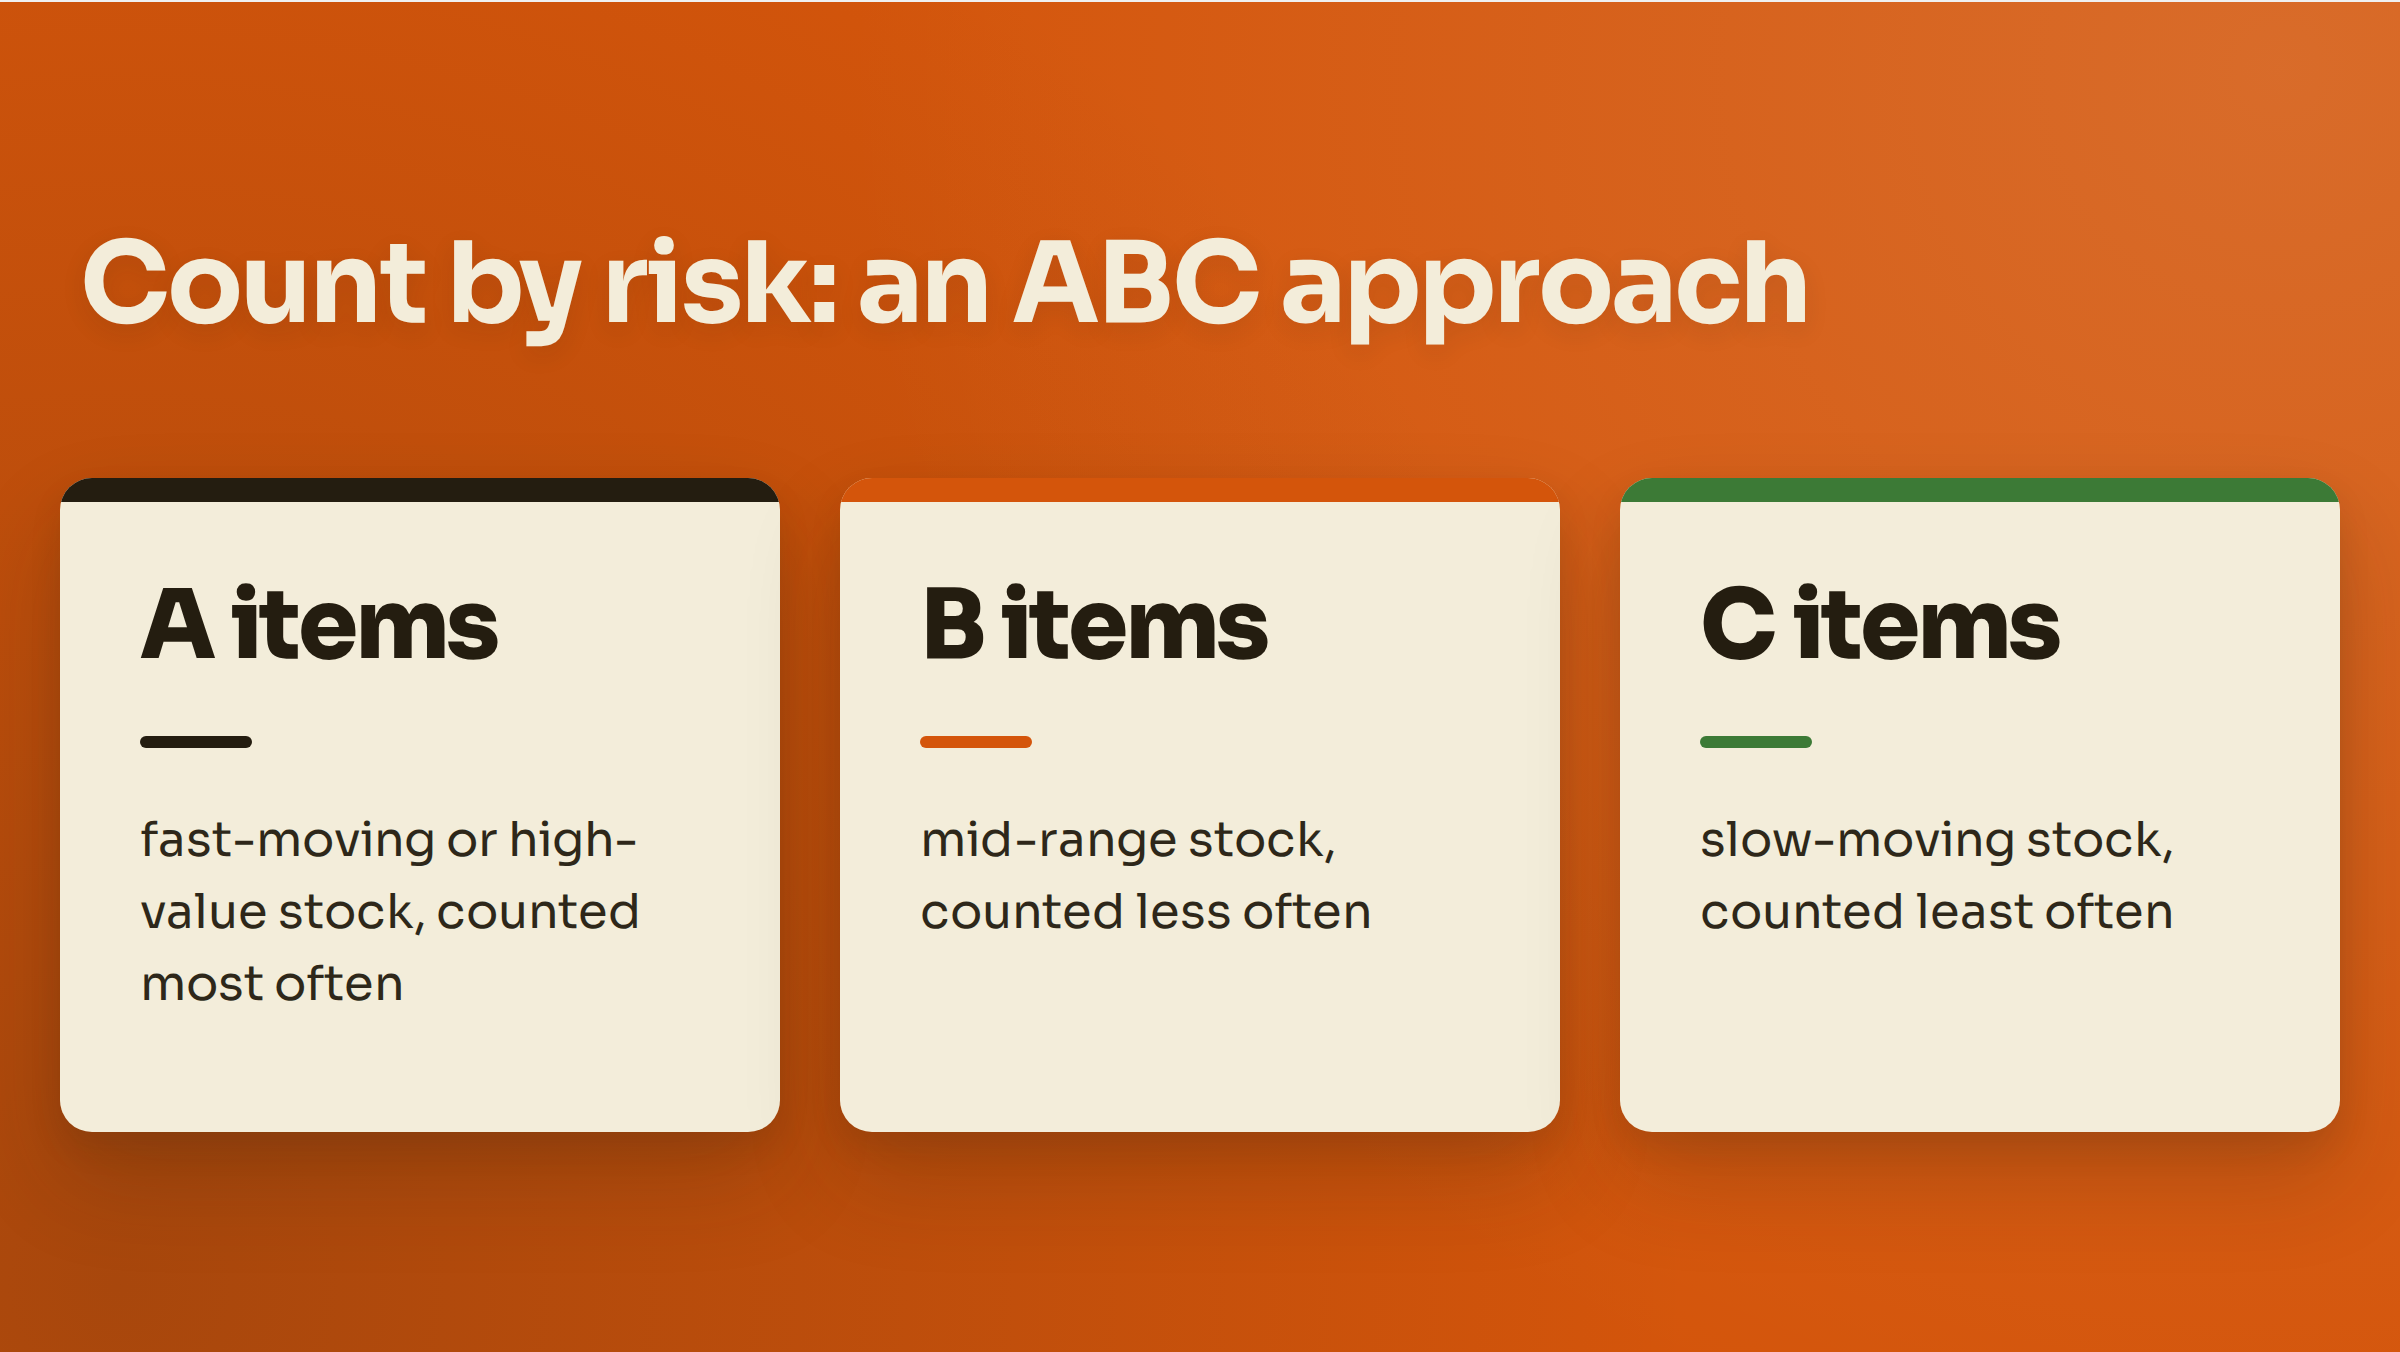
Not all stock carries the same risk. Use an ABC approach to prioritize your cycle counting schedule:
- 'A' items: High-value, high-velocity, or high-risk SKUs. Count these most frequently (e.g., weekly or monthly).
- 'B' items: Mid-range items. Count these quarterly.
- 'C' items: Low-value, slow-moving stock. Count these once or twice a year.
3. Use Blind Counts to Ensure Honesty
A "blind count" means the counter is not shown the expected system quantity. They are given a location and an SKU and told to count what is physically there. This prevents the natural human tendency to simply confirm the number on the screen. The system then compares the physical count to the book quantity, flagging any variance for investigation. It’s a simple but powerful control for ensuring the count itself is accurate.
4. Record Who, When, and What
Every count is a data point. Your system must record the essentials for every count performed:
- Who performed the count.
- The exact date and time.
- The location and SKU.
- The quantity found.
What to do with a variance
Finding a variance is the start of the process, not the end. The goal is not just to correct the number but to understand why it was wrong. A variance is a symptom of a broken process, and just adjusting the stock level without finding the cause means the problem will happen again.
1. Recount Before You Adjust
Never adjust your system based on a single count. The first step is always to have a different person recount the location. More often than not, the "variance" was a simple counting error, stock hidden at the back of the rack, or an item in an adjacent bin. A recount is the fastest way to rule out human error.
2. Investigate the Transaction History
If the recount confirms the variance, your team needs to become detectives. Pull the full transaction history for that SKU and location since its last clean count. Look for specific events:
- GRN Verification: Was the stock received correctly? Was it booked to the right client? Poor receiving discipline is a primary source of variances.
- Put-away: Was it put away in the wrong bin?
- Picks: Was a similar-looking SKU picked by mistake? Was a short-pick not recorded?
- Moves: Was a replenishment or consolidation move left unconfirmed in the system?
3. Tell the Client with Evidence
Once you find the cause, communicate it to the client clearly and with evidence. Don't just say, "We found a shortage of 10 units." Instead, say, "Our investigation found that 10 units were put away in bin A-02 instead of A-01 during receipt #54321. We have corrected the location in the system, and both bins have been recounted to confirm the total quantity." This turns a negative situation into a demonstration of your operational control and transparency.
When a full stock take is still right
While the rolling cycle count is the superior day-to-day control for a 3PL, there are four specific situations where a full, wall-to-wall stock take (or physical inventory) is the right—and often necessary—call.
1. Year-End or an Audit That Needs a Wall-to-Wall Number
Client auditors often require a complete physical inventory count to verify the existence and condition of stock as of the financial reporting date. Under auditing standards such as International Standard on Auditing (ISA) 501, auditors may need to attend and observe the count themselves. In this case, a cycle counting program is not a substitute. You must schedule and perform a full count with a hard cut-off for transactions.
2. A Client Contract That Requires One
Some client contracts explicitly mandate an annual or semi-annual full stock take. If it’s in the contract, you do it. The key is to ensure the contract also specifies who pays for the labor and operational downtime. Treat it as a billable project, schedule it with the client, and execute it according to the agreed procedure.
3. Taking Over Another Warehouse's Stock
When you onboard a new client and take over stock from their previous 3PL or their own facility, a full count is non-negotiable. This count establishes your opening baseline. Without it, you risk inheriting all the previous operator's inventory problems. Count everything, document any discrepancies against the handover paperwork, and get the client's sign-off on the opening balance before you start operations. This single act protects you from being blamed for pre-existing shortages.
4. After a System Migration or Major Disruption
After a significant operational change—like a WMS migration, a major warehouse re-layout, or recovery from a prolonged system outage—a full stock take is a prudent way to reset and validate your entire inventory. It confirms that all balances, locations, and ownership data have been transferred correctly. This is a critical step in the process of counting opening stock during a WMS implementation, ensuring you start with clean, reliable data.
Where Binsy fits
The challenge of the cycle count vs physical inventory discussion highlights a core need for 3PLs: a system built for multi-client operations. A generic WMS tracks inventory; a 3PL system must track inventory *by owner* and link every action to a billable event.
Binsy is the warehouse management and billing system designed specifically for third-party, multi-client warehouses. It is built on the principle of client-level segregation on a shared floor, ensuring that even if two clients' products are in adjacent bins, their stock records and billing are kept entirely separate. It handles items and pallets side by side on the same floor.
Crucially, with Binsy, a billing event is written as each move happens. This means the work you do—receiving, put-away and picking—is captured for billing in real-time. You no longer have to reconstruct invoices from paperwork at month-end. This is one of the key ways how a 3PL WMS differs from a standard WMS. Binsy, the FreighAI warehouse product, runs together with FreighAI today. To see how it works in a live environment, you can see your floor in Binsy.
Frequently Asked Questions
What is the difference between a cycle count and a physical inventory?
A cycle count is the process of counting a small, specific portion of your inventory on a continuous, rolling schedule while the warehouse continues to operate. A physical inventory (also known as a stock take) is a one-time event where you count all inventory items in the entire warehouse, which usually requires pausing operations to ensure an accurate snapshot.
What does stock take mean?
The term "stock take" (or stocktake) is commonly used in the UK, India, and other Commonwealth countries. It has the same meaning as a "physical inventory" in the US: the physical counting and verification of all stock on hand at a specific point in time to reconcile physical quantities with inventory records.
How often should a 3PL cycle count?
A 3PL should be cycle counting continuously. The frequency for specific items should be based on risk, using an ABC analysis. High-value, fast-moving 'A' items might be counted weekly or monthly. Slower-moving 'C' items might be counted once or twice a year. The exact schedule should be part of your inventory control policy and agreed upon with your clients.
Can cycle counting replace a stock take?
For day-to-day operational inventory control, a robust cycle counting program is superior to and can often replace the need for frequent full stock takes. However, it cannot always replace them entirely. Full stock takes are still typically required for annual financial audits, client contractual obligations, warehouse takeovers, or after major system migrations, as they provide a complete, wall-to-wall verification on a specific date that auditors and contracts may demand.
Sources & References
This article draws on research and data from the following verified sources:
From reading to the rack.
Bring one client's rate card and one month of invoices. We'll walk your flow through Binsy and show where the billing events would have written themselves.
Book a walkthroughKEEP READING